‘My mortgage has gone up already’: How rising interest rates are hitting people’s pockets
On Thursday, the Bank of England raised interest rates for the first time in over three years as part of its efforts to curb inflation connected to the ongoing conflict in Iran. Experts warn that further increases may take place over the next 18 months, given the continued impact of the war on global food, fuel, and energy prices. While higher interest rates can lead to improved savings returns, they also drive up borrowing costs. This means many people in the UK could face pricier mortgages, credit cards, and personal loans, intensifying financial challenges amid the rising cost of living.
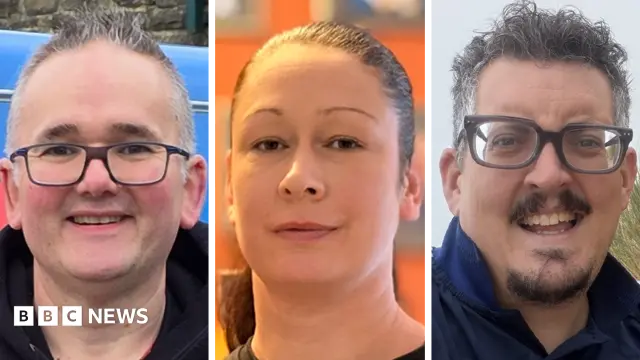
Peter Gill, 48, who operates a tiling business in Halifax, is among approximately 1.3 million Britons with mortgages that vary according to the Bank of England’s base rate. Since lenders add a margin on top, any rise in rates directly increases his monthly repayments. Following the recent quarter-point hike, Peter expects to pay about £45 more each month on his mortgage and worries that payments might continue to rise. Although he is aware that fixed-rate mortgages could offer more predictable costs, he believes switching now would be more costly and has decided to remain on his current tracker deal. Meanwhile, rising expenses affect many areas of Peter’s life. His family’s food, gas, and electricity bills have climbed, while his business faces higher labour costs due to a national minimum wage increase and raw material price inflation related to the Iran conflict. To cope, he’s been working roughly six and a half days a week.
Fixed-rate mortgage holders are not necessarily shielded from the effect of rising interest rates either. Dawn Fazackerley-King, a Pilates instructor living near Ipswich, is set to experience a significant financial impact when she remortgages. Having taken out a five-year fixed deal at 1.4% in January 2022, the best option she can now secure is a 5.69% rate for two years. This change will increase her monthly mortgage bills by approximately £200. Dawn and her husband have a combined income of around £70,000, and despite carefully reviewing their finances, they admit there is “no more obvious fat to trim.” Both work full time, so additional income through extra jobs is not feasible. She describes the situation as stressful and faces the challenge of managing these added costs without receiving any extra benefits in return.
Credit card users may also feel the pinch. When the Bank of England hikes its base rate, credit card companies often raise their interest charges after about a month’s notice, impacting those carrying balances. Ben Thomas, 41, from Shropshire, is among those affected. After leaving his chartered accountant career due to mental health issues in the Covid pandemic, he retrained as a paramedic but has struggled financially, accumulating £52,000 in debt. Although most of his interest payments have been paused by arrangement, he still faces charges on about £2,000 of credit card debt and is anxious about potential increases in repayments. Alongside roughly £300 a month in debt repayments and a £760 mortgage payment, Ben’s family is also burdened by rising food and energy costs. Simon Trevethick of StepChange, the debt charity assisting Ben, notes a 20% rise in support requests this year and warns that if borrowing costs continue to increase, more households may seek help in the coming months
On air now
Low-Fi Lounge